Graham Capital, a US$22B hedge fund, just showed how big the gap is between its quant and macro books.
Argya Whisnuputra Oct 10, 2026 2 min read
Follow Buysiders
Graham Capital’s Quant Funds Outpace Its Macro Strategy by Up to 3.8 Times in 2026
Graham Capital Management’s quantitative strategies have outperformed its macro fund by a wide margin in 2026, according to performance figures reported by Reuters on October 7.
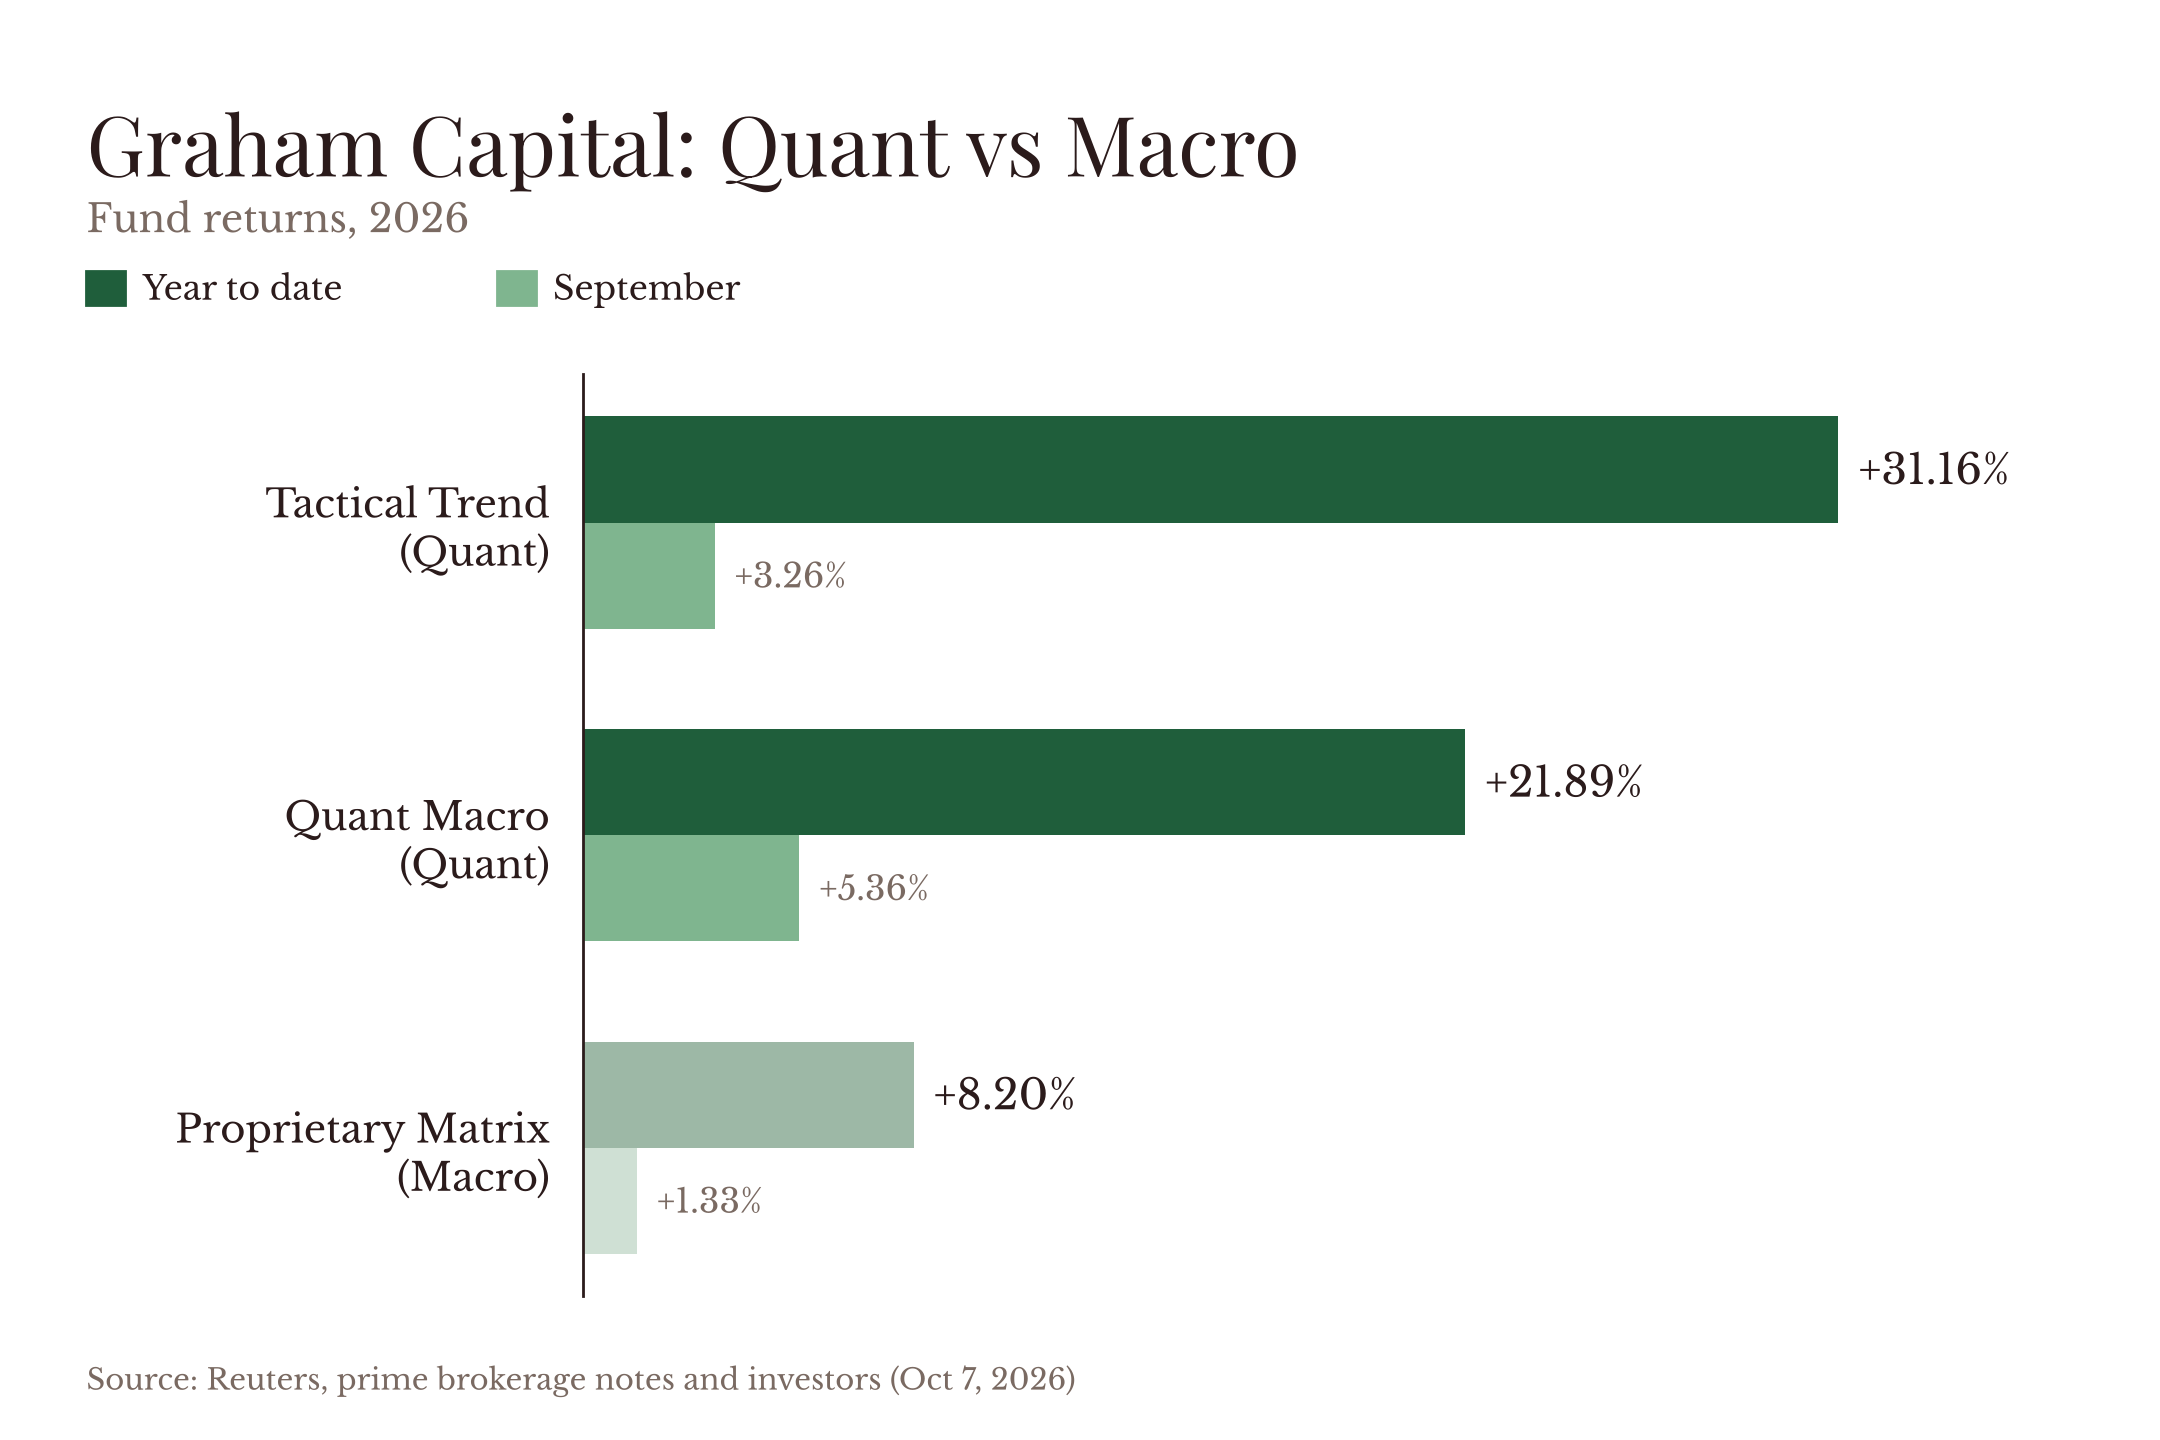
The $22 billion firm’s Tactical Trend fund returned 31.16% in the first nine months of the year, while its Quant Macro fund gained 21.89%. The firm’s Proprietary Matrix fund, classified as a macro strategy, returned 8.20% over the same period.
Tactical Trend’s year-to-date return is 3.8 times that of Proprietary Matrix, a difference of 22.96 percentage points. Quant Macro’s return is 2.7 times higher, a difference of 13.69 percentage points.
September performance
Quant Macro was Graham’s strongest fund in September, gaining 5.36%. Tactical Trend rose 3.26% and Proprietary Matrix added 1.33%. Quant Macro’s monthly return was 4.0 times that of the macro fund.
The Société Générale trend index, a benchmark for trend-following managers, gained more than 4% in September, according to Reuters. Quant Macro outperformed the index for the month, while Tactical Trend trailed it.
Bond market backdrop
The gains coincided with a global sell-off in government bonds. The US 10-year Treasury yield climbed from around 4% at the end of February to above 5.2%, and reached 5.342% on October 1, its highest level since 2002, Hedgeweek reported, citing the Financial Times. French, British and Italian government bonds also saw heavy selling.
Systematic funds that follow persistent price trends took large short positions in government debt, as the Iran conflict, rising energy costs and strong US economic data raised expectations of sticky inflation and higher rates. Brent crude has gained roughly 40% since the conflict began in February, trading at $102.31 a barrel on October 1.
According to CNBC, commodity trading advisors were short Treasurys ahead of September’s bond rout. Those positions added to earlier gains from bullish dollar bets and long oil positions taken before the Iran war. “CTAs are crushing the rest of the hedge fund world this year,” said Andrew Beer, managing member at Dynamic Beta Investments.
Wider hedge fund results
Reuters reported that hedge fund returns were uneven in September, with surging yields, rising oil prices and volatile AI stocks prompting selling, while quantitative strategies posted gains.
Among other large managers, Bridgewater Associates’ Pure Alpha macro fund returned 18.4% in the first nine months of the year. Graham’s Tactical Trend fund exceeded that figure by 12.76 percentage points, and Quant Macro by 3.49 percentage points.
Separately, the International Monetary Fund said on October 6 that hedge fund assets stood at roughly $13 trillion in early 2026, up from $4 trillion in 2013. The IMF said growth in the industry has come primarily through leverage, including synthetic leverage through derivatives.
Comments